The LIBOR Scandal Might Destroy the Banking Industry

Get your news from a source that’s not owned and controlled by oligarchs. Sign up for the free Mother Jones Daily.

The recent settlement with Barclays Bank over its LIBOR1 fixing fraud has gotten…. some…. attention. Not a lot of attention, though. Why is that, given that this fraud potentially affected trillions of dollars in assets?

I think the obvious answer is that (a) it’s really complicated and (b) everyone’s a little vague about just who got ripped off here. On a listserv I subscribe to, a seemingly knowledgeable participant2 said the victims of the scam include investors who owned floating rate notes, LIBOR-linked CDs, or pay-fixed-receive-floating interest rate swaps; or anyone who traded LIBOR contracts on a U.S. futures exchange and lost money. And let’s face it: that doesn’t sound much like widows and pensioners, does it?
What’s more, the LIBOR scam wasn’t about pushing LIBOR systematically up or down. Sometimes it was pushed up, sometimes it was pushed down, depending on whatever happened to be good for the Barclays trading desk on any given day. So even if you are a widow or a pensioner with a CD linked to the LIBOR rate, it’s not really clear if you were ever hurt.

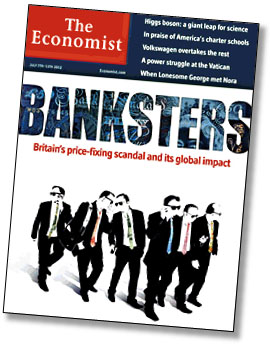
Nonetheless, it’s a big deal, and I think the Economist pretty much nails it here:

The attempts to rig LIBOR […] not only betray a culture of casual dishonesty; they set the stage for lawsuits and more regulation right the way round the globe. This could well be global finance’s “tobacco moment”….Despite the risks of banker-bashing, a clean-up is in order, for the banking industry’s credibility is shot, and without trust neither the business nor the clients it serves can prosper.

Right now the scandal is limited to Barclays, but that’s just because they decided to cooperate with regulators early on and therefore got keelhauled first. (Also, admittedly, because the Barclays board provided MBA courses of the future with an almost textbook case of how not to handle the news of a gigantic price fixing scandal.) UBS is said to be next in line, and other banks that haven’t cooperated as willingly will take longer to prosecute. In theory, though, the news is likely to be even worse once those cases finish up.

Roughly speaking, the view from inside Barclays is that they’re being treated unfairly. They cooperated, after all, and they say that other banks were way more involved in the LIBOR-fixing scam than they were. If that’s true, one of two things will happen. Either this scandal will explode way beyond the financial press, where it’s mostly played out so far. Or it will turn out that declining to cooperate makes it really hard to prosecute the other banks and Barclays will look like idiots for doing so. I’m not sure which to put my money on.

1LIBOR is the London Interbank Offered Rate. It’s basically the current interest rate banks charge each other to borrow money, and it changes on a daily basis. So if you have an adjustable rate mortgage, for example, your interest rate might be LIBOR + 3, or something like that.

2How’s that for a reliable source?
I'm hopeful because of readers like you. Will you pitch in today?

We see the headlines on a weekly basis: the claw backs in public media, the gutting of The Washington Post, the bending over backwards to appeal to Trump and his allies.

But not here.

When Mother Jones started publishing 50 years ago, our founders made a critical decision: to be a reader-supported nonprofit. They knew that no corporate owner would be interested in a muckraking newsroom; they also knew that no muckraking newsroom would be interested in following the agenda of a corporate owner.

And so, we’ve been reader-funded for half a century. We rely on contributions from our readers—readers like you—whether it’s $50, or $15 a month, or whatever fits your budget. People give what they can, and every donation makes a difference for our newsroom, which has grown tremendously—in size and reach and renown—since its inception in 1976.

You may be wondering: What does it take to publish an investigation? And what does my donation actually fund? The answers are one and the same: It takes people, resources, and time. And that’s what your donation funds directly.

Every donation Mother Jones receives from readers fortifies our newsroom, whether we’re covering underreported scandals out of Washington, DC, or the most important news of the day. And right now, each donation will be doubled thanks to a $50,000 match. So when you make a donation, it’ll go twice as far.

Your support keeps us going. If you’re able, donate today.

Thanks for reading.

—Monika Bauerlein, CEO

I'm hopeful because of readers like you. Will you pitch in today?

We see the headlines on a weekly basis: the claw backs in public media, the gutting of The Washington Post, the bending over backwards to appeal to Trump and his allies.

But not here.

When Mother Jones started publishing 50 years ago, our founders made a critical decision: to be a reader-supported nonprofit. They knew that no corporate owner would be interested in a muckraking newsroom; they also knew that no muckraking newsroom would be interested in following the agenda of a corporate owner.

And so, we’ve been reader-funded for half a century. We rely on contributions from our readers—readers like you—whether it’s $50, or $15 a month, or whatever fits your budget. People give what they can, and every donation makes a difference for our newsroom, which has grown tremendously—in size and reach and renown—since its inception in 1976.

You may be wondering: What does it take to publish an investigation? And what does my donation actually fund? The answers are one and the same: It takes people, resources, and time. And that’s what your donation funds directly.

Every donation Mother Jones receives from readers fortifies our newsroom, whether we’re covering underreported scandals out of Washington, DC, or the most important news of the day. And right now, each donation will be doubled thanks to a $50,000 match. So when you make a donation, it’ll go twice as far.

Your support keeps us going. If you’re able, donate today.

Thanks for reading.

—Monika Bauerlein, CEO

We Recommend

Latest

Sign up for our free newsletter

Subscribe to the Mother Jones Daily to have our top stories delivered directly to your inbox.

Get our award-winning magazine

Save big on a full year of investigations, ideas, and insights.

Subscribe

INDEPENDENT. BECAUSE OF YOU.

Mother Jones has no billionaires calling the shots—just readers like you making fearless reporting possible

Donate